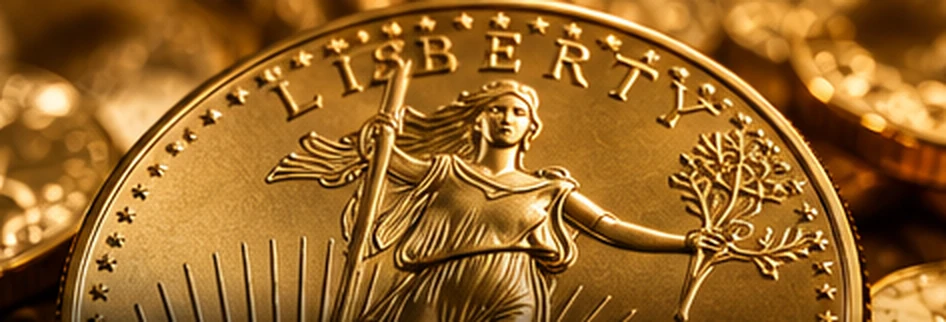
Search for “IRA-approved gold coins” and you'll encounter a wall of dealer listings. The real question is not whether a merchant has placed a badge on a product. It is which statutory exception the exact coin or bullion product may meet, whether the custodian will hold it, and what the dealer charges above its metal value.
Key distinction: Internal Revenue Code §408(m) sets out a coin exception for certain specified coins and a separate bullion exception based on fineness and trustee possession. A product can have an impressive official mint design and still require product-specific eligibility verification.
The statutory map: two routes
The IRS says that IRA investments in collectibles can be treated as taxable distributions, but §408(m)(3) provides exceptions for particular coins and qualifying bullion. The statute identifies U.S. gold coins described by specified paragraphs of 31 USC §5112(a), certain U.S. silver and platinum coins, and state-issued coins. Separately, qualifying gold, silver, platinum and palladium bullion must satisfy the relevant fineness rule and a trustee-possession requirement.
This means “99.5% minimum gold” is a commonly useful bullion screening number, not a universal description of every exception for coins.
Four important examples to investigate
| Product | Why it matters | Caution |
|---|---|---|
| American Gold Eagle bullion coin | U.S. Mint says 22-karat, 91.67% gold and explicitly describes IRA inclusion | Qualifying coin type does not permit casual personal possession |
| American Gold Buffalo bullion coin | U.S. Mint describes .9999 fine gold | Check exact coin, bullion status, and custodian requirements |
| High-fineness gold bars | May qualify under the bullion exception | Fineness, refiner/product details and trustee possession matter |
| Rare or proof collector coins | Can carry significant numismatic premiums | Do not assume every collectible edition is an appropriate IRA purchase; verify eligibility and resale economics independently |
Why the Gold Eagle breaks the simple purity slogan
According to the U.S. Mint, the one-ounce American Gold Eagle contains a full troy ounce of pure gold plus alloy metal that makes the entire coin heavier and harder-wearing. Its overall metal composition is 91.67% gold, 3% silver, balance copper. It is not secretly 99.5% pure. It is a specially described U.S. coin, so the coin exception matters. This is a legal distinction rather than a technical loophole in how purity is measured.
Read the Gold Eagle paradox before relying on a simplified chart.
Gold content and purchase price are not the same
Suppose a one-ounce gold coin contains one troy ounce of pure gold. If the spot benchmark is hypothetically $2,500 per troy ounce and a dealer asks $2,800, the premium above spot is $300 or 12% relative to the metal benchmark. No conclusion about a fair price follows merely from that percentage: mint premiums, market conditions, availability and dealer spread all matter. You still need to know what the dealer will pay to buy the same product back.
A rare coin may command a much larger premium unrelated to the metal alone. Its potential collectible value may be difficult to establish and difficult to recover. IRA eligibility and investment suitability are separate issues.
Physical form matters
A bar stamped with a fineness may still need checking for the actual producer, serial/inventory details, weight, and whether your custodian accepts that SKU. Coins are usually priced by the fine gold content, not only gross weight. Verify weights in troy ounces, which differ from ordinary avoirdupois ounces. Do not convert product pictures into purity certifications.
A practical buyer checklist
- Obtain the manufacturer's exact product name and year, if relevant.
- Ask which subsection of §408(m)(3) the provider believes applies.
- Get the custodian's written acceptance of that exact product and custody arrangement.
- Ask for the metal's fine troy ounces, benchmark spot price and the timestamp of that quote.
- Get total purchase price, premium, shipping, administration and storage in writing.
- Ask for a binding or clearly described indicative same-day buyback bid; understand any uncertainty.
- Prefer transparent, comparable bullion pricing over pressure to buy a supposedly rare coin without independent evidence.
What this guide cannot certify
We cannot inspect a product's provenance through a web photo, certify its assay, or promise that a specific custodian will accept it. The IRS does not publish a universal dealer-approved shopping cart. The safest language is potentially qualifying until the product, statute and custody arrangement have been checked.
Frequently asked questions
Does the U.S. Mint sell bullion directly to me? The U.S. Mint says its bullion coins are distributed through authorized purchasers, not sold directly to consumers through its ordinary bullion program.
Are Gold Eagles only 91.67% gold? Yes, by overall alloy composition. The one-ounce version still contains one troy ounce of fine gold plus alloy metal.
Do collectible proofs always qualify? Do not generalize from a dealer's label. Eligibility, custody acceptance and the potentially high collectible premium need separate review.
Can I include silver, platinum or palladium instead? Certain forms can qualify under the statute. See our four-metals eligibility guide.
Primary sources and review notes
Reviewed October 30, 2026. Verify current rules and account documents before acting. Fee and performance examples are hypothetical. IRA Gold is not a tax, legal or investment adviser.